

 Articles
Her Own Money: What Every Woman Should Know About Wealth
By Yelena Martino, Group CEO Signet Capital Management Group It might be a bank manager addressing your husband, though the account is joint. It might be a lawyer explaining your father’s estate…
8 Οκτωβρίου 2026 · 09:39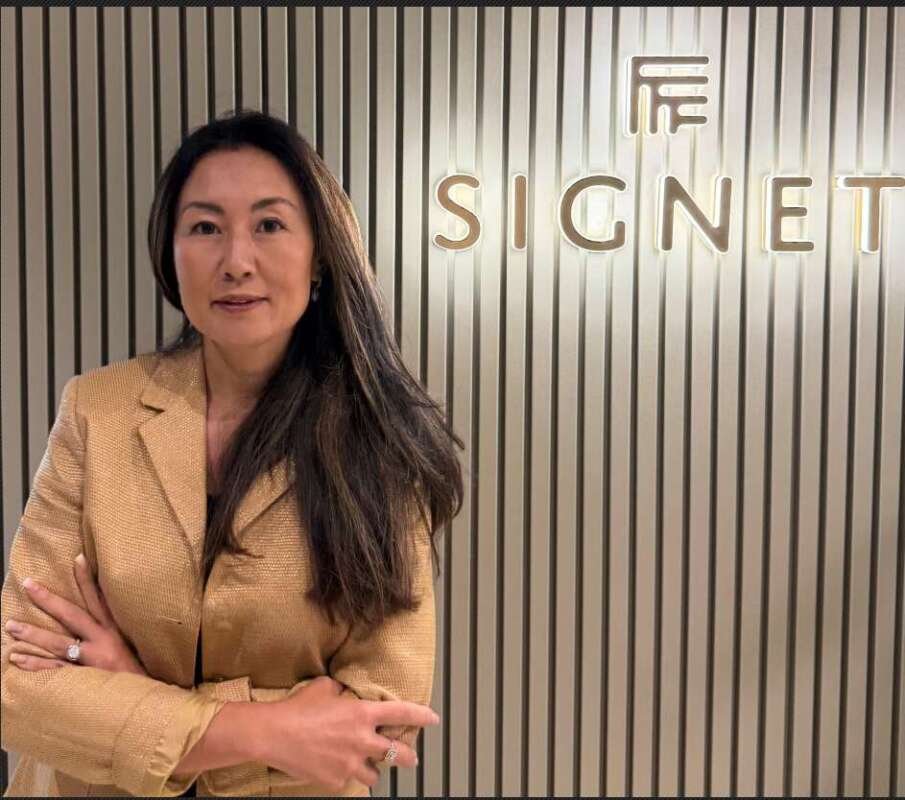
By Yelena Martino, Group CEO
Signet Capital Management Group
It might be a bank manager addressing your husband, though the account is joint. It might be a lawyer explaining your father’s estate to your brother. It might be subtler than that: the statements arrive in his name, the password is in his head, and you have always meant to ask.
You run a household budget to the cent. You negotiate with builders, schools, employers and teenagers. You may well run a company. Yet when the conversation turns to investments, pensions and what happens in thirty years, a surprising number of capable women step back and let someone else hold the pen.
This article is an argument for picking it up. There is nothing mysterious about wealth management, but the numbers for women are different, and nobody else will plan around them for you.
The arithmetic of being a woman
A woman’s financial life has less money coming in and more years to pay for. Four facts explain most of it.
- You will probably live longer. Across Europe, women outlive men by around five years. That is five more years of rent, food, healthcare and birthdays for grandchildren, and they come at the expensive end of life.
- You will probably earn less. The pay gap has narrowed but not closed. A smaller salary means smaller savings and a smaller pension, every year, for decades.
- Your career is more likely to pause. Children, ageing parents, a partner’s job abroad. Each break is reasonable. Together they leave holes in a pension record that nobody mentions until you are 60. In the European Union, women’s pensions are on average about a quarter lower than men’s.
- You are more likely to end up managing alone. Divorce and widowhood are common, and most married women will at some point be the only adult in charge of the family’s money. Too many meet their own finances for the first time in the worst month of their lives.
There is a fifth fact, and it is a happier one. When women do invest, they tend to do it well. Several large studies of ordinary investors have found that women’s returns match or slightly beat men’s, largely because women trade less, panic less and do not confuse confidence with skill.
So women are perfectly good at investing. The trouble is that too many keep their savings in a bank account, where inflation takes a small bite each year.
Case study: one woman, two endings
Elena is not a real person. She is a composite of women any wealth manager has met, and the numbers are illustrative.
At 30 she is a marketing manager, newly married, earning well. At 34 she has her first child and steps back from work for eight years. At 54 her marriage ends. Both endings share every one of those facts.
Ending one
Elena and her husband divide the work the way many couples do. He is “good with money”, so he handles the investments. She handles everything else.
Her salary, when she has one, goes on groceries, school shoes, holidays and birthday presents. His goes into a flat, a portfolio and a pension, all in his name, because it was simpler at the time. She signs what he puts in front of her, including a guarantee on a loan for his business.
She never opens the statements, and she tells herself this is trust. In truth she is a little afraid of looking foolish.
At 54 she is sitting in a lawyer’s office learning the vocabulary of her own life. She has €15,000 in a savings account, an eight-year gap in her pension record, and her name on a debt she does not understand. Whatever she is owed will be decided by other people, slowly, and at a cost.
Ending two
Same woman, same husband, same children, same ending to the marriage. Three things are different.
First, at 30 she sets up a transfer of €500 a month into a plain, diversified investment portfolio in her own name. It is not a secret and it is not a protest. It is simply hers.
Second, when she stops work, the couple agree that the transfer continues from the family income. Raising their children is work for the household, so the household funds her future while she does it.
Third, once a year, the two of them sit down with one page listing everything they own and owe, and whose name is on it. She reads before she signs. She asks the question that feels foolish. She declines the guarantee.
If her portfolio earns an average of 4% a year above inflation, which is a reasonable long-run assumption and never a promise, €500 a month becomes roughly €235,000 by the time she is 54. If she keeps going to 60, it is about €335,000.
The divorce still hurts, but she can afford a good lawyer and a home of her own, and she goes into the negotiation knowing what the family owns.
Seven rules for any woman
These apply whether you are 25 or 65, single or married, earning a salary or running the home.
- Own something in your own name. An account, a portfolio, a pension. Joint finances are fine, but you should also have money that needs no one else’s signature.
- Start now, with whatever you have. Time does most of the work. On the same assumptions as Elena, €500 a month from age 30 reaches about €335,000 by 60. Start at 40 and it reaches about €180,000. A ten-year delay costs nearly half.
- Keep a reserve, then invest the rest. Six to twelve months of living costs belongs in cash. Beyond that, cash loses value to inflation every year, and for most women the bigger danger is holding too much of it.
- Make the core boring. Diversified across the world, cheap to hold, easy to sell. You do not need to pick shares or watch markets. You need to keep contributing and leave it alone.
- Pay yourself through the career breaks. If you step back for the family, agree that the family keeps funding your pension and savings. Have that conversation before the break begins.
- Read before you sign. Loans, guarantees, company directorships, tax returns. If your name is on it, the consequences are yours, and “my husband dealt with it” will not protect you.
- Choose an adviser who talks to you. Regulated, clear in writing about fees, and willing to explain until you understand. If they address their answers to the man beside you, find another one.
If you have a daughter, add an eighth rule. Talk to her about money early and often, in the same tone you would use with a son.
The six moments that matter
Most of a financial life is routine. A handful of moments decide the rest, and each one comes with a question worth asking in advance.
Marriage. What is mine, what is yours, what is ours? A marital agreement is not a prediction of failure. It is a conversation held while you still like each other.
Children. Who pays for the parent who steps back? Settle the answer in euros per month.
Divorce. Do I know what we own? The woman who can answer that on day one saves herself months, money and sleep.
Widowhood. Could I run everything tomorrow? Know where the accounts, policies, passwords and wills are. Make no large decision for a year. Grief is a bad time to sell a house, and people with proposals tend to appear quickly.
Inheritance. What is this money for? A lump sum arriving in your fifties may be the largest you ever handle. Put it somewhere safe and take six months before you commit it to anything.
Moving abroad. If you followed a partner’s career to another country, you may have left behind a job, a pension scheme and a professional network. Check what you can still pay into at home, find out what you are entitled to in the new country, and make sure your name is on the lease, the bank account and the residency papers. Check too that your will works wherever you hold assets.
Pick up the pen
Wealth, for most women, has little to do with handbags or yachts. It means being able to leave a job, a city or a marriage if you have to, and to stay because you want to. It means helping a child without asking permission, and growing old without becoming anyone’s worry.
You already have the skills. You plan years ahead, you notice what others miss, and you carry on through tired evenings and uncertain months. Investing asks for the same things.
So open the statements this week. Ask the question you have been putting off. Set up the transfer, however small.
This article is general information, not personal investment, tax or legal advice. Rules on pensions, marital property and inheritance differ by country and by circumstance; speak to a regulated adviser and a lawyer before acting.
Πηγή – Cyprus Times
ΔΙΑΦΗΜΙΣΗ
Σχετικά άρθρα
Articles Articles
Μαραγκός: «Χτίζουμε τη νέα εποχή»
ΠΡΙΝ ΑΠΟ 1 ΛΕΠΤΑ Ελλάδα
Κυψέλη: Δεκτή η προσωρινή διαταγή – Οι κάτοικοι θα λάβουν όλα τα στοιχεία για τις καθιζήσεις και τις φθορές από το Μετρό
ΠΡΙΝ ΑΠΟ 1 ΛΕΠΤΑ Κύπρος